The physical method of money transfer has completely changed to digital finance due to the emergence of the digital rupee, UPI and digital lending platforms. A smartphone is enough to transfer money without visiting a branch.
What Is Digital Finance?
Digital finance refers to financial services which are provided through digital media such as UPI, internet banking, digital payments and digital wallets. Hence, it changes the way financial activities follow traditional payment methods. However, convenience does not mean risk-free.
How Has UPI Changed Everyday Payments?
Unified Payments Interface is the most popular example of digital finance. It allows users to transfer money conveniently without following traditional steps, which are time-consuming. However, it is highly relevant for small payments within a certain limitation of the number of transactions per day. On the other hand, RBI warns users regarding protection of sensitive information such as PIN, OTP, Password along with suspicious links and messages.
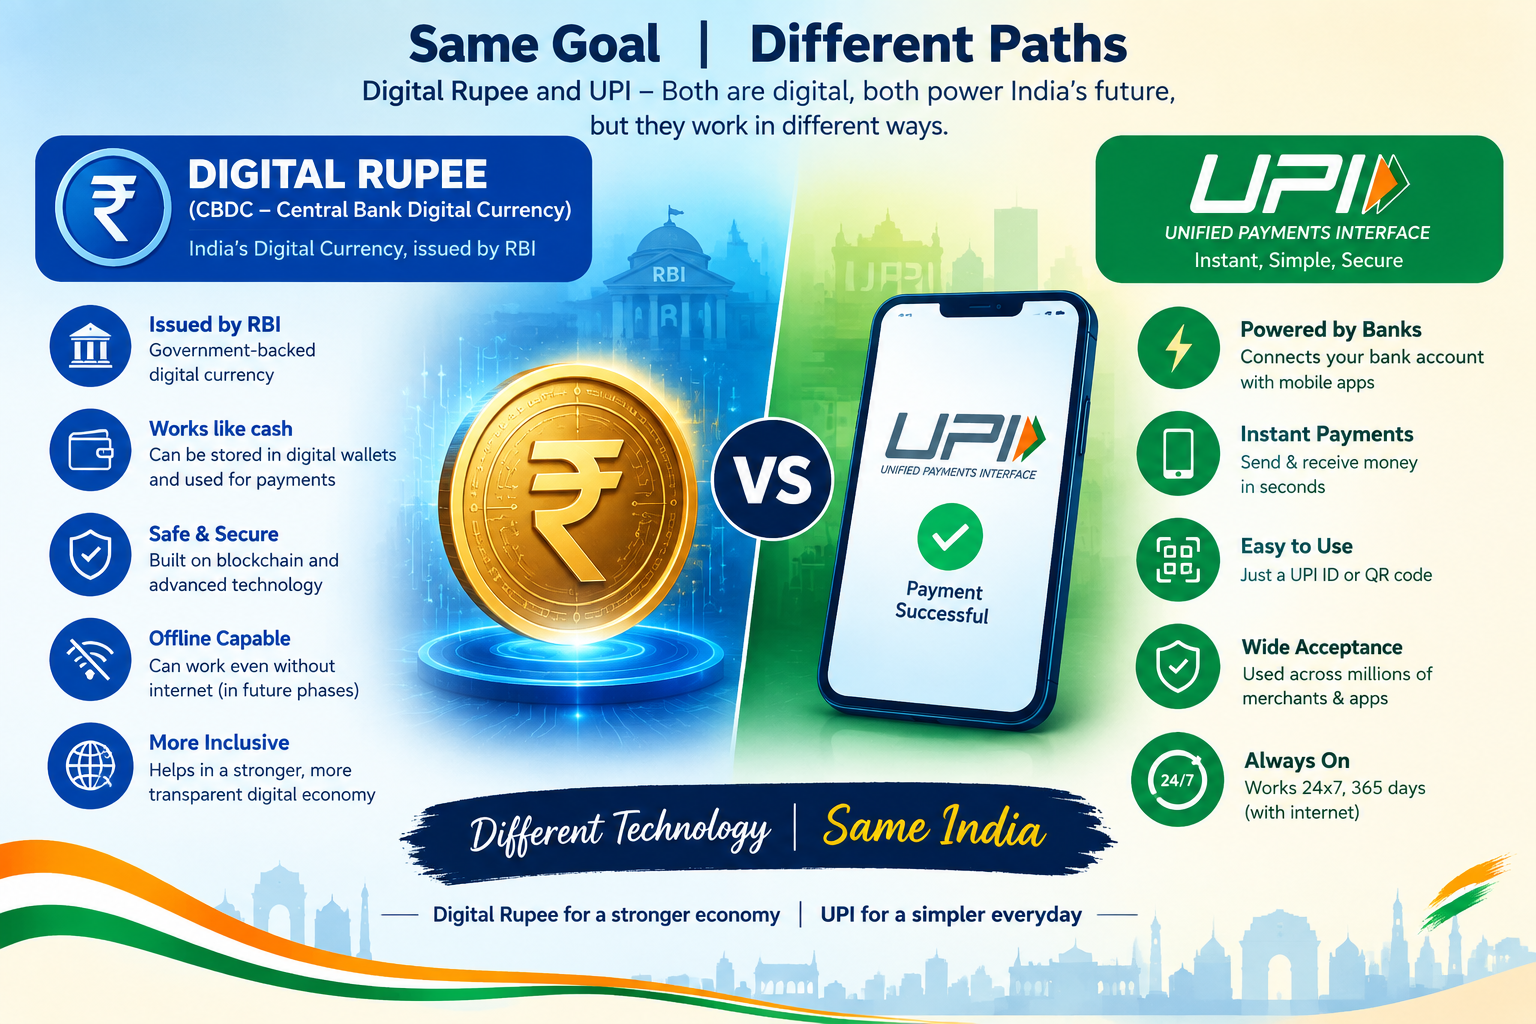
Digital Rupee vs UPI: Are They the Same?
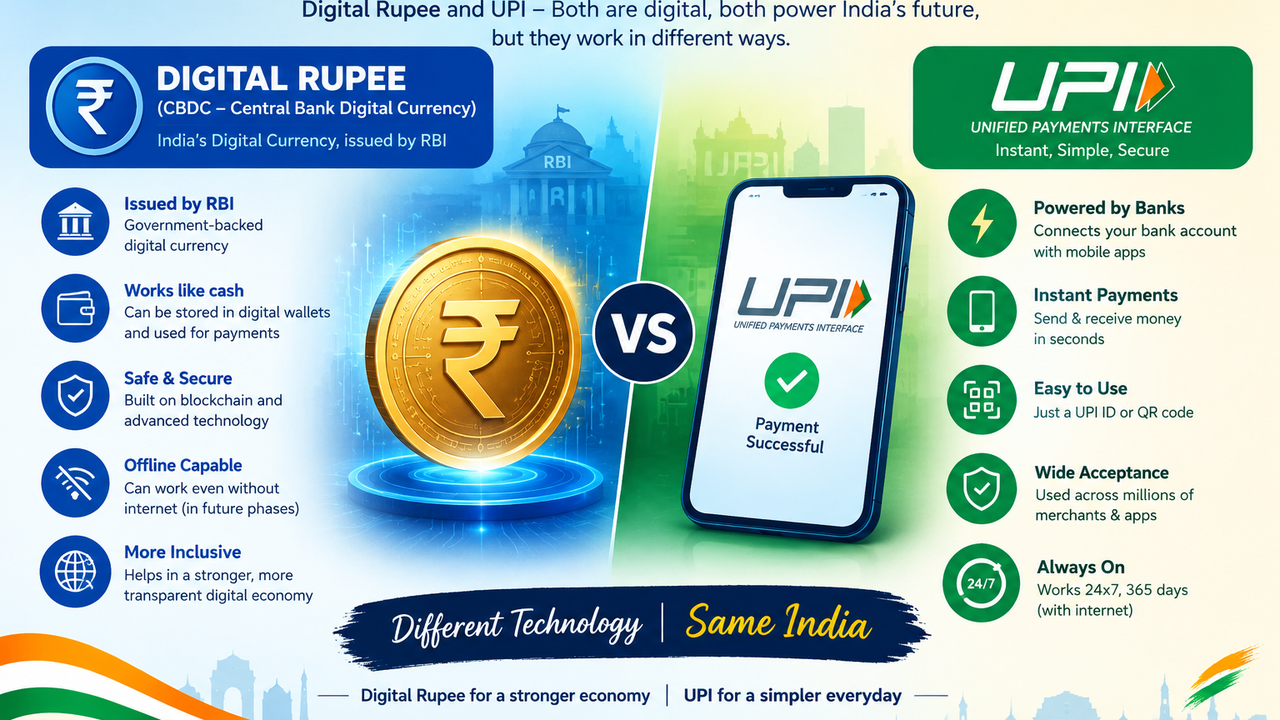
There is a misconception in digital finance about the difference between Digital Rupee (e₹) and UPI. The RBI has described e₹ as the digital form of the rupee, whereas UPI is a payment system or mechanism. Additionally, e₹ can be stored separately in a digital wallet, and it represents a liability of the RBI.
Hence, the easy explanation is:
UPI = a way to make payments
e₹ = a digital form of money
Importance of Digital Rupee
The digital rupee is a digital currency approved by the Central Bank. According to the RBI, it is a legal tender and does not pay interest when held in a digital wallet. It is important for programmable payments, government benefit transfers, and specific-purpose payments. In this regard, RBI has clearly discussed programmability, where digital funds can be designed for specific purposes.
Role of AI in Changing Digital Finance
AI makes digital finance more convenient for users to transfer money easily. AI is used by financial institutions for fraud detection, risk assessment and customer support. AI can assess large amounts of data, which is humanly impossible. Additionally, AI-based systems make processing faster. However, AI usage is questionable, as AI is used by scammers to collect personal information. The financial system is not efficient, and it is evolving over time.
Now the question is “Is Digital Finance Better Than Traditional Banking?”
Yes, digital services are far better than traditional banking systems because of faster transactions, greater convenience, easy accessibility and time efficiency. However, financial literacy is low in developing countries, which often creates complexity in using new financial technology.
Conclusion
The digital rupee can be used as part of digital financial services with the use of UPI.
Be the first to comment on this article.